Driver based budgeting gives a Kenyan SME a more realistic way to plan revenue, costs, cash flow and growth. Instead of taking last year’s expenses and adding a percentage, driver based budgeting starts with the operational activities that actually create financial results.
For example, a restaurant may budget from expected customers, average spend, food costs and staff shifts. A distributor may use units sold, selling prices, inventory days and delivery costs. A professional-services firm may use billable employees, utilisation, billing rates and collection days.
That makes driver based budgeting different from simply copying last year’s income statement into a spreadsheet.
For a Kenyan SME, the approach can be particularly useful because business conditions can change quickly. Sales volumes, supplier prices, salaries, financing costs, exchange rates, tax obligations and customer payment behaviour can all affect the amount of cash available to the business.
A good budget should therefore answer more than:
“How much will we spend?”
It should answer:
“What business activity causes this revenue or cost, what assumptions are we making, and what happens to cash if those assumptions change?”
That is the purpose of driver based budgeting.
What Is Driver Based Budgeting?
Driver based budgeting builds the budget around measurable business drivers rather than simply adjusting historical figures. The method connects operational activity to revenue, costs, working capital and cash flow.
A traditional incremental budget might look like this:
Last year’s marketing cost = KSh 2 million
Next year’s marketing budget = KSh 2.4 million
The increase is 20%, but the model does not explain why.
A driver based budgeting approach asks different questions:
- How many customers are we targeting?
- What is our expected customer acquisition cost?
- How many campaigns will we run?
- How many sales should each campaign generate?
- What is the expected average transaction value?
- How many sales employees do we need?
- What will each employee cost?
- How much inventory is required to support the sales plan?
- How quickly will customers pay?
- How much supplier credit will be available?
The budget then becomes a mathematical representation of the operating plan.
For example:
Customers × Average Transaction Value = Revenue
or:
Employees × Average Salary = Payroll Cost
or:
Units Sold × Cost Per Unit = Cost of Goods Sold
or:
Revenue ÷ 365 × Receivable Days = Accounts Receivable
These relationships form the foundation of driver based budgeting.
Why Driver Based Budgeting Matters for Kenyan SMEs
Driver based budgeting helps an SME understand why financial results are expected to change rather than simply predicting that they will change. It makes budgets easier to explain, update and test.
Many SMEs prepare annual budgets because management, lenders, investors or accountants request them.
The problem is that a static annual budget can become outdated quickly.
Suppose a Nairobi wholesaler budgets KSh 120 million in annual sales based on the previous year’s revenue.
Six months later, management discovers that:
- Sales volumes are below target.
- Customers are taking longer to pay.
- Supplier prices have increased.
- Inventory is turning more slowly.
- Transport costs have increased.
- The company hired more staff than originally planned.
The original budget may still show the annual target.
But management needs to understand the underlying drivers.
Driver based budgeting makes those drivers visible.
Instead of saying:
“Revenue is 10% below budget.”
Management can identify:
“Sales volume is 7% below plan, average selling price is 2% below plan, and collections are 15 days slower.”
That information is much more useful for decision-making.
Start With the Business Model
Effective driver based budgeting starts with understanding how the business actually makes money. The budget should reflect the company’s operating model rather than forcing every business into the same spreadsheet structure.
Before creating budget figures, identify the basic revenue engine.
Retail business
Possible drivers include:
- Number of transactions
- Average basket size
- Store traffic
- Conversion rate
- Product mix
- Gross margin
- Stock turnover
Distributor
Possible drivers include:
- Units sold
- Customers served
- Average selling price
- Supplier pricing
- Gross margin
- Delivery kilometres
- Inventory days
- Customer credit days
Professional-services business
Possible drivers include:
- Number of consultants
- Billable hours
- Utilisation rate
- Billing rate
- Client retention
- New contracts
- Collection period
Restaurant
Possible drivers include:
- Number of customers
- Average spend per customer
- Table turnover
- Food cost percentage
- Staff shifts
- Delivery orders
Construction company
Possible drivers include:
- Projects under contract
- Project milestones
- Materials required
- Labour hours
- Equipment utilisation
- Contract payment terms
The first step in driver based budgeting is therefore to identify the variables that genuinely drive financial performance.
Step 1: Identify Your Revenue Drivers
Revenue should normally be built from operational assumptions rather than selected as a target number. Driver based budgeting makes the assumptions behind revenue explicit so management can challenge and update them.
Consider a Kenyan services company with five consultants.
Suppose:
- 5 consultants
- 160 available hours per month each
- 70% billable utilisation
- KSh 4,000 average billing rate per hour
The monthly revenue model becomes:
5 × 160 × 70% × KSh 4,000 = KSh 2.24 million
Annualised:
KSh 2.24 million × 12 = KSh 26.88 million
Now management can change the drivers.
If utilisation rises to 75%, the revenue forecast changes.
If billing rates increase to KSh 4,500, the forecast changes.
If one consultant leaves, the forecast changes.
This is much more useful than simply typing “KSh 27 million” into the budget.
The same principle applies to a product business.
For example:
10,000 units × KSh 2,500 average selling price = KSh 25 million revenue
The budget can then test different sales volumes and prices.
That is the power of driver based budgeting.
Step 2: Separate Volume, Price and Mix
Driver based budgeting becomes more informative when management separates volume, price and product or customer mix. Revenue growth can come from selling more units, charging more per unit or changing what customers buy.
Imagine an SME sells three product categories.
| Product | Units | Average Price | Revenue |
|---|---|---|---|
| A | 5,000 | KSh 1,000 | KSh 5M |
| B | 3,000 | KSh 2,000 | KSh 6M |
| C | 1,000 | KSh 5,000 | KSh 5M |
| Total | KSh 16M |
Management can now ask:
- What if Product A volume increases?
- What if Product B prices increase?
- What if Product C declines?
- Which product has the strongest gross margin?
- What happens if customers shift from high-margin products to low-margin products?
A simple percentage-growth budget may hide these differences.
A driver based budgeting model exposes them.
Step 3: Build Costs From Their Drivers
Not every expense should be forecast using the same percentage increase. Driver based budgeting separates fixed, variable and semi-variable costs so that spending changes appropriately when business activity changes.
Consider payroll.
Instead of:
Last year’s payroll + 10%
use:
Number of employees × Salary + Benefits + Statutory Costs
If the business plans to hire five additional employees, the budget reflects the hiring schedule.
Similarly, rent may be driven by:
Number of locations × Monthly Rent
Transport may be driven by:
Delivery Trips × Average Cost Per Trip
Production costs may be driven by:
Units Produced × Cost Per Unit
Sales commissions may be driven by:
Sales × Commission Rate
Cloud software may be driven by:
Users × Cost Per User
These drivers make the budget easier to explain.
They also make scenario planning much faster.
Step 4: Model Headcount Properly
Headcount is one of the most important SME budget drivers because employee costs can become a major fixed or semi-fixed expense. Driver based budgeting should model when employees join, what they cost and what operational capacity they add.
A headcount schedule should ideally show:
- Position
- Number of employees
- Start date
- Basic salary
- Allowances
- Employer costs
- Annual increases
- Bonuses or commissions where applicable
For example:
| Role | Current | Planned | Start Month |
|---|---|---|---|
| Sales | 4 | 6 | April |
| Operations | 5 | 7 | July |
| Finance | 1 | 2 | October |
This prevents a common budgeting mistake: assuming that every employee costs the business for twelve full months.
If a new employee starts in July, the budget should reflect six months rather than twelve.
For SMEs, that difference can materially affect cash requirements.
Step 5: Connect Sales to Working Capital
Driver based budgeting should not stop at profit. Revenue growth can consume cash when customers pay slowly or when inventory must be purchased before sales are collected.
This is one of the most important concepts for SME budgeting.
Suppose an SME forecasts:
KSh 60 million annual revenue
But customers take an average of 60 days to pay.
A simplified receivables calculation would be:
KSh 60 million ÷ 365 × 60 = approximately KSh 9.86 million
That means almost KSh 10 million could be tied up in receivables under those assumptions.
Now suppose the business reduces the average collection period to 45 days.
The approximate receivables balance becomes:
KSh 60 million ÷ 365 × 45 = approximately KSh 7.40 million
The difference is about:
KSh 2.46 million
The company has not increased revenue.
It has improved cash conversion.
This is why driver based budgeting should connect the income statement with working capital and cash flow.
Step 6: Budget Inventory Using Operational Drivers
Inventory should be linked to expected sales, purchasing requirements and stock-turn assumptions. Driver based budgeting helps an SME identify how much cash must be committed to stock before the related sales are collected.
A distributor might forecast:
- Annual cost of sales: KSh 36 million
- Inventory holding period: 45 days
A simplified inventory estimate is:
KSh 36 million ÷ 365 × 45 = approximately KSh 4.44 million
If inventory days increase to 60:
KSh 36 million ÷ 365 × 60 = approximately KSh 5.92 million
The difference is about KSh 1.48 million.
That additional cash requirement may not appear as an obvious problem in the income statement.
It appears in the balance sheet and cash flow.
A good driver based budgeting process therefore asks:
How much stock do we need to support the sales plan?
not simply:
What was inventory last year?
Step 7: Build a Cash Budget From the Drivers
The cash budget should translate operating assumptions into actual expected cash movements. Driver based budgeting is particularly valuable when an SME has rapid growth, tight liquidity or significant working-capital requirements.
A cash budget should consider:
Cash inflows
- Customer collections
- Cash sales
- Loans
- Equity injections
- Asset disposals
- Other receipts
Cash outflows
- Supplier payments
- Salaries
- Rent
- Taxes
- Loan repayments
- Capital expenditure
- Marketing
- Utilities
- Other operating costs
The timing matters.
A business can be profitable but short of cash.
For example:
January sales: KSh 5 million
Customer payment terms: 60 days
The accounting revenue may be recognized in January, but much of the cash may arrive in March.
Meanwhile, suppliers may require payment in 30 days.
That creates a financing gap.
A driver based budgeting model exposes this timing difference.
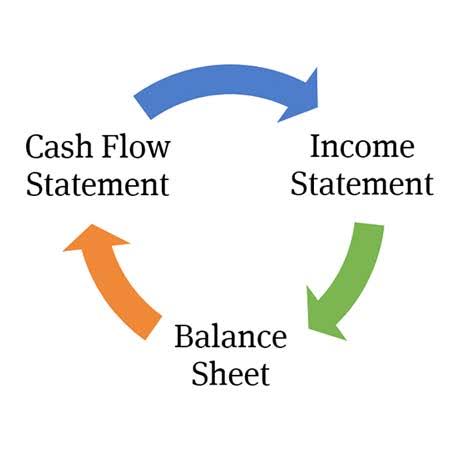
Driver Based Budgeting and the Three Financial Statements
The strongest driver based budgeting models connect the budget to the income statement, balance sheet and cash flow statement. This shows how operational decisions affect profitability, financial position and liquidity simultaneously.
The basic relationships are:
Operating drivers → Revenue
Revenue and cost drivers → Profit
Credit terms → Receivables and payables
Purchasing assumptions → Inventory
Capital expenditure → Fixed assets
Financing assumptions → Debt and equity
All movements → Cash flow
This is why driver-based budgeting and a financial modelling process often work together.
For businesses that need a more integrated forecast, the budget can become the operating layer of a three-statement financial model.
Driver Based Budgeting vs Traditional Budgeting
Traditional budgeting is not inherently wrong, but it can become rigid when historical percentages replace operational analysis. Driver based budgeting provides greater visibility into what causes financial results to change.
| Traditional Budgeting | Driver Based Budgeting |
|---|---|
| Starts with historical spending | Starts with business activity |
| Often uses percentage increases | Uses operational drivers |
| Can encourage budget padding | Makes assumptions more visible |
| May be difficult to update | Drivers can be changed quickly |
| Focuses heavily on expense lines | Connects operations and finance |
| Can hide cash implications | Highlights cash requirements |
| Often static | Easier to model scenarios |
The difference is not that one method always produces a better number.
The difference is how the number is produced and how easily management can understand it.
Use Actual Results to Update the Budget
Driver based budgeting works best as a continuous management process rather than a document prepared once a year. Actual performance should be compared with budget drivers and assumptions should be updated when business conditions change.
Suppose the budget assumed:
- 1,000 customers
- KSh 5,000 average transaction
- 30-day collection period
Actual results show:
- 900 customers
- KSh 5,300 average transaction
- 48-day collection period
Revenue may be closer to expectations than the customer count suggests because average transaction value increased.
But cash may be significantly weaker because customers are taking longer to pay.
A conventional budget variance may simply say:
Revenue: 3% below budget
A driver-based analysis can say:
Customer volume: below plan
Average transaction value: above plan
Collection days: materially above plan
That is much more actionable.
Build Driver-Based Variance Analysis
Variance analysis should explain why actual performance differs from the budget. Driver based budgeting allows management to separate volume, price, efficiency and timing effects rather than treating every variance as an unexplained percentage.
Useful variance categories include:
Volume variance
Did the business sell more or fewer units than expected?
Price variance
Did the average selling price differ from the assumption?
Mix variance
Did customers buy a different combination of products or services?
Cost-rate variance
Did supplier prices, wages or other unit costs change?
Efficiency variance
Did the business use more resources than expected?
Timing variance
Did an expense or receipt occur earlier or later than expected?
Working-capital variance
Did customers pay more slowly or did inventory remain longer than planned?
This allows management to focus on the actual cause.
Driver Based Budgeting for Different Kenyan SME Sectors
The drivers used in driver based budgeting should reflect the sector and operating model of the SME. There is no universal list of budget drivers that works equally well for every company.
Retail
Key drivers:
- Customer traffic
- Conversion rate
- Average basket
- Units sold
- Gross margin
- Stock turnover
- Store count
Wholesale and distribution
Key drivers:
- Units sold
- Average selling price
- Customer count
- Delivery costs
- Inventory days
- Receivable days
- Supplier payment terms
Manufacturing
Key drivers:
- Production volume
- Machine capacity
- Material cost per unit
- Labour hours
- Scrap rate
- Energy consumption
- Production efficiency
Professional services
Key drivers:
- Headcount
- Billable hours
- Utilisation
- Billing rate
- Client count
- Retention
- Collection period
Hospitality
Key drivers:
- Occupancy
- Average daily rate
- Guests
- Food and beverage revenue
- Labour cost
- Seasonality
E-commerce
Key drivers:
- Website traffic
- Conversion rate
- Average order value
- Customer acquisition cost
- Repeat purchase rate
- Delivery cost
- Returns
The correct drivers depend on how the business generates revenue and incurs costs.
Connect Driver Based Budgeting With Accounting Records
A budget should be grounded in reliable accounting information. Driver based budgeting becomes less useful when historical revenue, expenses, receivables, inventory or cash balances are incomplete or unreliable.
Before building next year’s budget, management should reconcile:
- Bank accounts
- Sales
- Purchases
- Receivables
- Payables
- Inventory
- Payroll
- Loans
- Fixed assets
- Tax balances
- Owner transactions
This is particularly relevant in Kenya because KRA’s income-and-expense validation framework compares declared figures against available information including TIMS/eTIMS, withholding tax and import records.
KRA also states that persons engaged in business are required to onboard eTIMS and issue electronic tax invoices, with specified categories of costs excluded from the eTIMS invoice requirement.
This means financial planning should not exist separately from accounting and tax records.
Where the underlying books need strengthening, bookkeeping and accounting support can help create a more reliable starting point for budgeting and forecasting.
Include Tax and Compliance Drivers
Tax should be included as a financial driver rather than added as an afterthought. A Kenyan SME’s budget should consider the timing and nature of its relevant tax obligations alongside operating assumptions.
Depending on the business, management may need to consider:
- Income tax
- VAT
- Withholding tax
- Payroll-related obligations
- Tax payment dates
- Tax credits
- Capital expenditure treatment
- Import-related costs
- Electronic invoicing requirements
The objective is not to turn the budget into a tax return.
It is to ensure that expected tax-related cash outflows are not ignored.
KRA’s current guidance states that income and expense validation uses available electronic invoicing and other tax data, while its 2026 materials also address accounting and accrual adjustments such as deferred income, prepayments, accrued expenses and inventory-related adjustments.
For an SME, this makes good record-keeping an important part of financial planning.
Management can also use tax compliance and advisory services when tax assumptions require specialist review.
Add Scenario Planning to the Budget
Driver based budgeting becomes significantly more useful when management can change key assumptions and immediately see the financial consequences. At minimum, SMEs should consider base, downside and upside scenarios.
For example:
Base case
- Revenue growth: 15%
- Gross margin: 35%
- Receivable days: 45
- Inventory days: 40
Downside case
- Revenue growth: 5%
- Gross margin: 31%
- Receivable days: 65
- Inventory days: 55
Upside case
- Revenue growth: 25%
- Gross margin: 37%
- Receivable days: 35
- Inventory days: 30
The objective is not to predict the future perfectly.
It is to understand the range of financial outcomes.
Management can then identify the assumptions that matter most.
For example, the budget may reveal that a 10-day increase in customer collection time has a greater cash impact than a 5% reduction in marketing expenditure.
That insight can influence management priorities.
Identify the Drivers That Matter Most
Not every variable deserves equal attention. Effective driver based budgeting identifies the small number of assumptions that have the greatest impact on revenue, profit or cash.
A business might have 200 expense lines but only 10 major financial drivers.
For example:
- Sales volume
- Average selling price
- Gross margin
- Customer collection days
- Inventory days
- Headcount
- Salary cost
- Rent
- Capital expenditure
- Debt repayments
These should receive more management attention than minor stationery expenses.
A sensitivity analysis can show which drivers have the largest impact.
This prevents the budgeting process from becoming an administrative exercise.
Common Driver Based Budgeting Mistakes
The biggest driver based budgeting mistakes occur when companies choose the wrong drivers, use unsupported assumptions or fail to connect the budget to cash. A sophisticated spreadsheet cannot compensate for weak business logic.
Common mistakes include:
Choosing drivers that management cannot measure
If customer acquisition data is unreliable, using it as a key driver may create false precision.
Using too many drivers
An overly complicated model can become difficult to maintain.
Ignoring seasonality
Retail, hospitality, agriculture and many other businesses can have substantial seasonal patterns.
Assuming every cost is variable
Rent, core salaries and many software costs may remain relatively fixed even when sales decline.
Ignoring collection timing
Profit does not automatically equal cash.
Ignoring inventory
Growth may require substantial upfront stock investment.
Treating the budget as a target rather than a model
The budget should help management understand the business rather than encourage arbitrary spending simply because it was included in the plan.
Failing to update assumptions
A budget built in January may become unrealistic by June if key business drivers have changed.
When Should a Kenyan SME Use Driver Based Budgeting?
Driver based budgeting is especially useful when an SME is growing, expanding, raising finance, managing tight cash flow or experiencing significant changes in its operating model.
It can be particularly valuable when:
- Revenue is growing rapidly
- Working capital is under pressure
- The business has several product lines
- The company is opening new branches
- Headcount is increasing
- Management is considering new equipment
- The company is applying for financing
- Investors require forecasts
- The business is preparing for valuation
- Profitability is changing
- Cash flow is unpredictable
A small business does not need a complicated financial department to benefit from the approach.
The model can start with a handful of meaningful drivers and become more sophisticated as the business grows.
How Adamjee Auditors Can Support Driver Based Budgeting
A useful driver based budgeting process combines operational understanding with accounting, cash-flow and financial-modelling discipline. Adamjee Auditors can support SMEs that need to turn accounting information into practical budgets, forecasts and management reports.
Support can include:
- Budget preparation
- Financial modelling
- Cash-flow forecasting
- Management accounts
- Budget-versus-actual analysis
- Working-capital analysis
- Scenario modelling
- Investor forecasts
- Financial reporting
- CFO advisory
- Tax and compliance support
Adamjee’s CFO advisory services include cash-flow management and financial modelling, making the service relevant for SMEs that need stronger financial planning and decision support.
Businesses preparing for investment or strategic transactions can also connect budgeting with Business Valuation Kenya and broader financial advisory work.
The objective is not simply to produce a budget spreadsheet.
It is to help management understand what must happen operationally for the financial plan to become achievable.
A Practical Driver Based Budgeting Framework
A practical driver based budgeting process can be implemented in a sequence: understand historical performance, identify drivers, forecast activity, translate activity into financial results, test scenarios and monitor actual performance.
Use this framework:
Understand
Review historical financial statements, accounting records and operating data.
Identify
Select the major revenue, cost, working-capital and financing drivers.
Quantify
Determine realistic assumptions for each driver.
Model
Translate the drivers into revenue, expenses, assets, liabilities and cash flows.
Test
Run downside, base and upside scenarios.
Approve
Agree the assumptions and financial targets with management.
Monitor
Compare actual performance with budget every month.
Explain
Investigate the driver behind each material variance.
Update
Revise forecasts when material assumptions change.
This creates a rolling financial-management process rather than a once-a-year budgeting exercise.
Driver Based Budgeting Checklist for a Kenyan SME
Before approving a budget, management should be able to identify the operational driver behind every major revenue and cost assumption. A good driver based budgeting process should also explain how those assumptions affect cash.
Check that the budget includes:
- Revenue drivers
- Volume assumptions
- Pricing assumptions
- Product or service mix
- Gross-margin assumptions
- Headcount plan
- Salary assumptions
- Variable operating costs
- Fixed operating costs
- Customer collection days
- Supplier payment days
- Inventory days
- Capital expenditure
- Debt repayments
- Financing requirements
- Tax-related cash requirements
- Opening cash
- Closing cash
- Base scenario
- Downside scenario
- Upside scenario
- Monthly budget-versus-actual analysis
- Driver-based variance analysis
- Documented assumptions
If these elements are present, the budget becomes much more than a list of expected expenses.
Final Takeaway
Driver based budgeting gives a Kenyan SME a practical way to connect operational activity with financial results. Instead of asking what last year’s figures should become, management asks what business activity will create next year’s revenue, costs, profit and cash flow.
The approach is straightforward:
Identify the drivers.
Quantify the assumptions.
Build the financial forecast.
Connect the forecast to cash.
Test different scenarios.
Compare actual results against the drivers.
Update the forecast when the business changes.
For a Kenyan SME, this approach can provide a clearer view of whether growth is profitable, how much working capital is required and when additional financing may be needed.
It also creates a stronger bridge between bookkeeping, financial reporting, management decisions and strategic planning.
A budget should not simply tell the owner how much the business intends to spend.
It should explain why the numbers look the way they do and what management can change when reality differs from the plan.
That is what makes driver based budgeting a practical financial-management tool rather than just another annual spreadsheet.
Gain Clarity and Confidence in Your Finances
Navigate the complexities of compliance, tax, and financial management with a trusted partner. Adamjee Auditors, a member of Santa Fe Associates International (SFAI), provides world-class audit, tax, and advisory services to help your business achieve its goals.
Schedule a consultation with our expert team in Nairobi or Mombasa to discuss your business needs.
Nairobi Office
1st Floor, Le’Mac Building, Church Road, off Waiyaki Way, Westlands
+254 717 908 241
madamjee@adamjeeauditors.co.ke
Mombasa Office
Suite 401, Motorwalla Building, Jomo Kenyatta Road
+254 750 053 053
info@adamjeeauditors.co.ke
Adamjee Auditors