Financial model mistakes startup founders make can undermine an otherwise strong business plan. A financial model may contain detailed projections, charts, formulas and investor metrics, yet still produce unreliable conclusions because the underlying assumptions, cash-flow mechanics or formulas are wrong.
The problem is rarely Excel itself.
Most financial model mistakes startup founders encounter come from translating a business plan into numbers without properly connecting the operating assumptions to revenue, costs, working capital, financing and cash flow.
A founder may know the business extremely well but still build a model that:
- Overstates revenue growth
- Underestimates expenses
- Ignores working capital
- Confuses profit with cash
- Uses unsupported assumptions
- Hardcodes projected figures
- Fails to connect the three financial statements
- Does not test downside scenarios
- Cannot be easily updated
- Does not reconcile with the accounting records
These financial model mistakes startup businesses make can become particularly costly when the model is being used for fundraising, debt financing, expansion, valuation or strategic planning.
A good financial model should not simply make the business look attractive.
It should help management understand what could happen.
This guide examines the five most important financial model mistakes startup founders should identify before relying on a model for major business decisions.
What Makes a Startup Financial Model Reliable?
A reliable startup financial model connects business activity to financial outcomes and allows management to test different assumptions. The model should be understandable, flexible, internally consistent and supported by reliable historical information.
Before examining individual financial model mistakes startup founders make, it helps to establish what a good model should accomplish.
A financial model should answer practical questions such as:
- How much revenue can the business realistically generate?
- What will gross margin look like?
- How much will the company spend?
- How much working capital will growth require?
- When will the company become cash-flow positive?
- How much funding is required?
- How long will the funding last?
- What happens if revenue is below expectations?
- What happens if costs increase?
- What happens if customers pay late?
- How does additional investment affect the business?
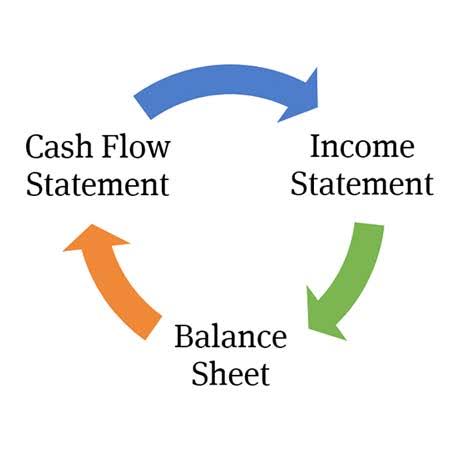
A properly constructed three-statement model normally connects the income statement, balance sheet and cash-flow statement so that assumptions flow through the financial statements dynamically.
This is important because one change should often have several financial consequences.
For example:
Higher sales → higher receivables → higher working capital → lower operating cash flow → potentially greater funding requirement.
If a model cannot reflect relationships like this, it may not be sufficiently robust for important decisions.
That is why identifying financial model mistakes startup founders make should be part of the preparation process before presenting a model to investors, lenders or a board.
Financial Model Mistake #1: Forecasting Revenue Without Business Drivers
The first major financial model mistake startup founders make is forecasting revenue as an arbitrary percentage rather than building it from measurable operating drivers. Revenue should be linked to customers, pricing, volume, transactions, retention or another identifiable source of sales.
One of the most common financial model mistakes startup businesses make is entering a revenue growth assumption such as:
2027 revenue growth = 50%
2028 revenue growth = 50%
2029 revenue growth = 50%
The spreadsheet calculates perfectly.
But the business logic may be weak.
Why 50%?
Where will the additional customers come from?
How many salespeople are required?
What marketing expenditure supports the growth?
Will the company have enough capacity?
Will customer churn remain constant?
Will pricing change?
A financial model should answer these questions.
Build revenue from operating assumptions
Suppose a startup sells software subscriptions.
Instead of entering annual revenue directly, the model could calculate:
Opening customers + new customers – churned customers = closing customers
Then:
Average customers × average monthly revenue per customer × 12 = annual recurring revenue
Now the revenue forecast has a commercial explanation.
If management wants revenue to grow faster, it must identify what needs to change.
Perhaps:
- More sales representatives are required
- Marketing expenditure must increase
- Conversion rates need to improve
- Customer churn must fall
- Average selling prices need to increase
- New products must be launched
This makes the model more useful.
The same principle applies to other industries.
A distributor might model:
Units sold × selling price
A hotel might model:
Available rooms × occupancy × average room rate
A manufacturer might model:
Production volume × selling price
A professional-services firm might model:
Billable employees × utilisation × billing rate
The exact formula changes by business.
The principle does not.
Revenue should emerge from the economics of the company.
This is one of the most important financial model mistakes startup founders should correct before sharing projections externally.
Why Revenue Assumptions Matter to Investors
Investors need to understand why projected revenue can grow, not merely see a large revenue number at the end of the forecast. Driver-based revenue modelling makes assumptions easier to challenge and defend.
Consider two startup models.
Model A
Revenue:
- Year 1: KSh 20 million
- Year 2: KSh 40 million
- Year 3: KSh 80 million
No explanation is provided.
Model B
Revenue is calculated from:
- Number of customers
- Customer acquisition
- Churn
- Average selling price
- Conversion rate
- Sales capacity
Model B is more useful because management can explain the mechanism behind growth.
If investors challenge the forecast, the founder can identify which assumptions drive the result.
That distinction is critical when reviewing financial model mistakes startup founders may not notice themselves.
Financial Model Mistake #2: Building Only a Best-Case Scenario
The second major financial model mistake startup founders make is assuming that the base forecast will unfold exactly as planned. A serious model should test downside conditions so management knows how much cash and funding the business may need if assumptions deteriorate.
Optimism is useful when building a company.
It is less useful when it becomes the only scenario in a financial model.
A founder may assume:
- Strong customer growth
- Falling acquisition costs
- Stable margins
- Fast collections
- Low employee turnover
- No major unexpected expenses
- Successful fundraising
- Rapid market adoption
Every assumption may appear reasonable individually.
The danger comes when several assumptions fail simultaneously.
That is why scenario modelling is essential when reviewing financial model mistakes startup founders make.
Use three core scenarios
A practical model should normally contain:
Base case
Management’s most reasonable expectation.
Downside case
A less favourable but plausible outcome.
Upside case
A stronger-than-expected outcome.
For example:
| Assumption | Downside | Base | Upside |
|---|---|---|---|
| Revenue growth | 15% | 30% | 45% |
| Gross margin | 42% | 48% | 53% |
| Customer churn | 8% | 5% | 3% |
| Collection period | 75 days | 45 days | 30 days |
| Payroll growth | 20% | 15% | 12% |
These figures are illustrative.
The actual assumptions should come from the company’s operating data, industry conditions and management plans.
The downside case is particularly important
Imagine the base case shows that a startup will have KSh 15 million in cash after 12 months.
That may appear comfortable.
But the downside scenario could reveal:
- Revenue 20% below plan
- Gross margin 5 percentage points lower
- Customers paying 30 days later
- Marketing expenditure 15% higher
The resulting cash position might be negative.
That changes the decision.
Management may need to:
- Raise capital earlier
- Delay recruitment
- Reduce discretionary expenditure
- Tighten credit terms
- Improve collections
- Delay expansion
- Adjust pricing
The purpose of scenario modelling is not to make the forecast look pessimistic.
It is to reveal financial risk before the business experiences it.
This is why scenario analysis should be part of any review of financial model mistakes startup founders make.
Financial Model Mistake #3: Confusing Profit With Cash
The third major financial model mistake startup founders make is treating projected profit as evidence that the company will have enough cash. Receivables, inventory, capital expenditure, debt repayments and other timing differences can create cash shortages even when the income statement shows profit.
This is one of the most dangerous financial model mistakes startup founders can make.
Consider a company that forecasts:
- Revenue: KSh 60 million
- Gross profit: KSh 24 million
- Operating expenses: KSh 18 million
- Operating profit: KSh 6 million
The founder may conclude that the company is financially healthy.
But suppose customers take 90 days to pay.
The company may have to pay suppliers after 30 days.
It may also need to purchase inventory before making the sales.
The company could therefore be profitable while struggling for cash.
Why working capital matters
Working capital generally involves items such as:
- Trade receivables
- Inventory
- Trade payables
- Other operating current assets
- Other operating current liabilities
A rapidly growing company can require more cash simply because more money becomes tied up in operations.
For example:
Higher sales
→ more credit sales
→ higher receivables
→ greater working-capital requirement
→ lower operating cash flow.
This relationship should appear in the model.
Capital expenditure also affects cash
A startup may purchase:
- Equipment
- Vehicles
- Computers
- Production machinery
- Office infrastructure
- Software systems
These purchases may not appear as an immediate operating expense in the same way as ordinary monthly costs, but they still require cash.
A strong model should therefore distinguish between:
Profitability
and
Cash movement.
This distinction is essential when correcting financial model mistakes startup founders make.
The Three-Statement Model Should Actually Connect
A three-statement model should dynamically connect the income statement, balance sheet and cash-flow statement. If each statement has been forecast independently, the model can hide inconsistencies and produce unreliable cash or funding requirements.
One of the strongest ways to address financial model mistakes startup founders make is to use an integrated three-statement structure.
The model should connect:
Income statement
Shows:
- Revenue
- Cost of sales
- Gross profit
- Operating expenses
- EBITDA
- Depreciation
- Interest
- Tax
- Net profit
Balance sheet
Shows:
- Cash
- Receivables
- Inventory
- Fixed assets
- Payables
- Debt
- Other liabilities
- Equity
Cash-flow statement
Shows:
- Operating cash flow
- Investing cash flow
- Financing cash flow
- Net change in cash
The three statements should interact.
For example:
Revenue increases
→ receivables may increase
→ working capital changes
→ operating cash flow changes
→ cash changes.
Similarly:
New borrowing
→ cash increases
→ debt increases
→ interest expense may increase
→ financing cash flow changes.
A model where these relationships are disconnected should receive careful review.
That is another major category of financial model mistakes startup founders should identify before an investor sees the model.
Financial Model Mistake #4: Hardcoding Forecast Numbers
The fourth major financial model mistake startup founders make is hardcoding projected results instead of creating formulas driven by clearly identified assumptions. A flexible model should allow management to change a key assumption and see the financial consequences automatically.
Hardcoding is not always wrong.
Historical financial information will often be entered as actual data.
The problem is hardcoding numbers that should be calculated.
For example, suppose the model contains:
2027 Revenue = KSh 50 million
2028 Revenue = KSh 75 million
2029 Revenue = KSh 100 million
If those figures have simply been typed into the forecast, changing the growth assumption becomes difficult.
A better model might contain:
2027 revenue × growth assumption = 2028 revenue
Then:
2028 revenue × growth assumption = 2029 revenue
Now management can change the growth assumption.
The model updates automatically.
Separate assumptions from calculations
A useful structure could contain:
Assumptions
- Customer growth
- Pricing
- Churn
- Gross margin
- Salaries
- Rent
- Marketing
- Working capital
- Tax
- Capital expenditure
Calculations
- Revenue
- Cost of sales
- Gross profit
- EBITDA
- Receivables
- Inventory
- Payables
- Cash
- Debt
This structure makes the model easier to review.
It also reduces the risk of one number changing while related calculations remain unchanged.
This is an important control when addressing financial model mistakes startup founders make.
Why Hardcoding Can Destroy a Model
Hardcoded forecast figures make scenario analysis difficult and can hide inconsistencies between financial statements. The more important a projected number is to the decision, the more important it is that the model shows how that number was calculated.
Suppose a founder changes expected revenue from KSh 50 million to KSh 40 million.
A properly structured model should automatically update:
- Cost of sales
- Gross profit
- Sales commissions
- Working capital
- Receivables
- Cash flow
- EBITDA
- Tax
- Funding requirement
If only the revenue figure changes, the model is not doing enough.
This is why hardcoding is one of the most common financial model mistakes startup founders should eliminate.
Financial Model Mistake #5: Creating Complexity Instead of a Decision Tool
The fifth major financial model mistake startup founders make is confusing spreadsheet complexity with financial quality. A model should be detailed enough to answer the decision at hand, but simple enough for management and investors to understand.
A founder-built model can contain:
- 25 worksheets
- Thousands of formulas
- Multiple dashboards
- Complex macros
- Hundreds of assumptions
- Several formatting systems
And still fail to answer:
How much cash will we need if sales are 20% below plan?
That is a problem.
The purpose of a financial model is not to demonstrate spreadsheet skill.
It is to support decisions.
Build the model around the question
If the model is for fundraising, it should answer:
- How much capital is required?
- What will the money finance?
- How long will the funding last?
- What milestones will be achieved?
- When might another round be required?
If the model is for expansion, it should answer:
- How much will expansion cost?
- How much additional working capital is required?
- When does the expansion break even?
- What happens if sales are slower?
If the model is for a valuation, it should help explain:
- Revenue growth
- Margins
- Free cash flow
- Capital expenditure
- Working capital
- Future cash flows
- Key risks
A model should therefore be designed around its purpose.
This is a crucial principle when reviewing financial model mistakes startup founders make.
The Hidden Financial Model Mistake: Ignoring the Accounting Records
A forecast is only as reliable as the historical information supporting it. Before building or reviewing a startup model, historical revenue, expenses, receivables, payables, cash, inventory and debt should be reconciled to the accounting records.
There is another problem that sits underneath many financial model mistakes startup founders make.
The starting numbers are wrong.
A founder may build a sophisticated forecast using:
- A sales spreadsheet
- Bank statements
- A bookkeeping file
- A separate payroll spreadsheet
- A manually prepared debt schedule
But if those sources do not reconcile, the forecast may begin from an unreliable base.
Before building a serious financial model, management should review:
- Trial balance
- General ledger
- Bank reconciliations
- Accounts receivable
- Accounts payable
- Inventory
- Fixed assets
- Loans
- Equity
- Historical revenue
- Historical expenses
For businesses that need stronger accounting foundations, Adamjee Auditors provides bookkeeping and accounting services covering the financial information businesses rely on for reporting and planning.
This makes accounting quality an important part of preventing financial model mistakes startup founders make.
Financial Model Mistakes Startup Founders Make With Working Capital
Working capital should be modelled using realistic collection periods, inventory requirements and supplier payment terms. Rapid revenue growth can consume cash when the business must fund operations before customers pay.
Working capital is frequently underestimated in startup models.
Consider a company growing rapidly from KSh 30 million to KSh 100 million in revenue.
If customers buy on 60-day credit, the increase in receivables can consume substantial cash.
If inventory must also increase to support sales, the funding requirement becomes larger.
At the same time, suppliers may provide only 30 days of credit.
The model should therefore consider:
- Debtor days
- Inventory days
- Creditor days
- Revenue growth
- Cost of sales
- Collection assumptions
- Supplier terms
This is another area where financial model mistakes startup founders make can produce a misleading cash runway.
Financial Model Mistakes Startup Founders Make With Hiring
Payroll should be modelled from actual hiring plans, salaries, benefits and timing rather than as a simple percentage of revenue. Headcount growth can materially affect cash burn before new employees generate additional revenue.
A startup may plan to hire:
- Five salespeople
- Two developers
- One finance manager
- Three customer-support employees
The model should show when each person joins.
It should also consider:
- Salary
- Benefits
- Recruitment costs
- Training
- Payroll taxes
- Annual increases
- Equipment
- Timing
A business that hires too early may burn cash unnecessarily.
A business that hires too late may fail to achieve its revenue plan.
This is why staffing assumptions should connect directly to the operating strategy.
Poor headcount assumptions are another common form of financial model mistakes startup founders should test.
Financial Model Mistakes Startup Founders Make With Fundraising
A fundraising model should show how much capital is needed, why it is needed and how long it is expected to last. The funding requirement should emerge from the operating model rather than being selected first and justified afterwards.
Suppose a founder decides:
“We need to raise KSh 50 million.”
The model is then built to justify KSh 50 million.
That reverses the process.
A stronger approach is:
Operating plan
→ hiring
→ marketing
→ product development
→ working capital
→ capital expenditure
→ cash burn
→ minimum cash requirement
→ funding gap.
The required funding then emerges from the model.
This creates a more defensible funding requirement.
It also helps investors understand exactly what their capital is expected to achieve.
For startups preparing for investment, Adamjee’s CFO advisory services can support financial modelling, cash-flow planning, investor readiness and management-level financial decision-making.
This is especially relevant when financial model mistakes startup founders make begin affecting fundraising discussions.
Financial Model Mistakes Startup Founders Make Before Valuation
Forecast assumptions can materially affect business valuation, particularly when valuation relies on future cash flows or earnings. Founders should therefore ensure the financial model is defensible before using it as an input to a valuation.
Financial modelling and valuation are closely connected.
For example, a discounted cash-flow approach requires assumptions about:
- Revenue
- Margins
- Operating expenses
- Taxes
- Capital expenditure
- Working capital
- Free cash flow
- Discount rates
- Terminal value
If revenue is overstated, the valuation can become overstated.
If margins are unrealistic, the same problem can occur.
If working capital is ignored, projected free cash flow may be inflated.
This makes financial model mistakes startup founders make particularly important when a company is preparing for fundraising, an acquisition, shareholder transaction or business sale.
Adamjee’s Business Valuation Kenya pillar explains the broader valuation process, including valuation methods, financial information, assumptions and factors that influence business value.
Financial Model Mistakes Startup Founders Make With Tax
Tax assumptions should be incorporated into financial models using the company’s actual circumstances and applicable Kenyan tax rules. Tax should not simply be inserted as an arbitrary percentage at the end of the forecast.
Tax can affect:
- Cash flow
- Profit
- Working capital
- Investment decisions
- Financing
- Capital expenditure
- Business valuation
Kenyan businesses also need to maintain reliable transactional records.
KRA states that persons engaged in business are required to onboard eTIMS and issue electronic tax invoices, with specific exceptions for certain expenses.
KRA also began validating income and expenses declared in income-tax returns against TIMS/eTIMS, withholding-tax and customs data from 1 January 2026.
That means the quality of accounting information supporting a financial model has become even more important.
A startup should therefore avoid building forecasts from incomplete or poorly controlled financial records.
For businesses needing support with the underlying tax position, Adamjee provides tax compliance and advisory services.
This accounting-to-tax connection should be considered when reviewing financial model mistakes startup founders make.
How to Review a Founder-Built Financial Model
A proper model review should test both mathematical integrity and commercial logic. The reviewer should examine formulas, historical data, assumptions, scenarios, working capital, cash flow and the relationship between the three financial statements.
A practical review of financial model mistakes startup founders make can follow several stages.
Review the purpose
First ask:
What decision is this model designed to support?
If the answer is unclear, the model may be too broad.
Review the historical data
Compare the model against:
- Financial statements
- Trial balance
- Bank balances
- Receivables
- Payables
- Inventory
- Debt schedules
Review the assumptions
Identify the assumptions that have the greatest effect on:
- Revenue
- EBITDA
- Cash
- Funding requirements
- Valuation
Review formulas
Check for:
- Broken references
- Hardcoded forecasts
- Inconsistent formulas
- Incorrect signs
- Circular references
- Missing calculations
- Incorrect period references
Review the scenarios
Change major assumptions.
Try:
Revenue -20%
Gross margin -5 percentage points
Collection period +30 days
Payroll +15%
Marketing +20%
Then examine the effect on cash.
This process can expose financial model mistakes startup founders may not see when reviewing their own spreadsheets.
A Practical Financial Model Mistakes Startup Checklist
Before sending a startup financial model to investors or lenders, founders should test revenue drivers, margins, working capital, cash, funding, scenarios and formula integrity. The model should also reconcile with reliable historical accounting records.
Use this review before an important meeting.
Revenue
- Is revenue linked to operational drivers?
- Are customer numbers realistic?
- Is pricing documented?
- Is churn included?
- Is seasonality relevant?
- Can management explain the growth rate?
Costs
- Are costs connected to business activity?
- Is headcount modelled?
- Are major expenses identified?
- Are one-off costs separated from recurring costs?
Working capital
- Are receivables included?
- Is inventory included where relevant?
- Are supplier payment terms included?
- Does growth create additional funding requirements?
Cash
- Does the cash-flow statement reconcile?
- Are capital expenditures included?
- Are loan repayments included?
- Is minimum cash modelled?
Funding
- Does the funding requirement emerge from the model?
- Is the use of funds clear?
- Is cash runway visible?
- Is another funding round likely under the downside scenario?
Scenarios
- Is there a base case?
- Is there a downside case?
- Is there an upside case?
- Can assumptions be changed easily?
Structure
- Are assumptions separated from calculations?
- Are formulas consistent?
- Are forecast numbers unnecessarily hardcoded?
- Does the balance sheet balance?
- Are error checks included?
This checklist addresses the most common financial model mistakes startup founders should correct before relying on a model.
When Should a Startup Get Its Financial Model Reviewed?
Professional review is particularly valuable before fundraising, major borrowing, expansion, acquisitions, valuation or other decisions where incorrect projections could materially affect the company. An independent review can identify errors that the original model builder may overlook.
A founder-built model does not automatically need to be replaced.
Sometimes it needs a focused review.
A review can examine:
- Revenue assumptions
- Gross margins
- Customer growth
- Churn
- Working capital
- Cash runway
- Debt
- Capital expenditure
- Tax
- Funding requirements
- Formula integrity
- Scenario analysis
- Valuation assumptions
The objective is not necessarily to rebuild every worksheet.
It is to identify the assumptions and calculations that materially affect the decision.
That is particularly useful when financial model mistakes startup founders make are concentrated in only a few key areas.
From Founder Spreadsheet to Investor-Ready Financial Model
An investor-ready model should connect the operating plan to financial results and make important assumptions easy to understand and challenge. Investors should be able to see not only what management expects to happen, but why.
A strong model should connect:
Business strategy
→ Operating assumptions
→ Revenue
→ Costs
→ Profitability
→ Working capital
→ Cash flow
→ Funding requirement
→ Investor outcomes
That chain is what makes financial modelling commercially useful.
It also explains why financial model mistakes startup founders make can become serious during due diligence.
Investors do not need a spreadsheet that looks complicated.
They need one that makes sense.
How Adamjee Auditors Can Help
Adamjee Auditors can help founders and finance teams review or develop financial models that support budgeting, forecasting, cash-flow planning, fundraising and strategic decisions. The objective is to produce a model that management can understand and use, rather than a spreadsheet that simply looks sophisticated.
Depending on the business, support can include:
- Reviewing a founder-built model
- Building a three-statement model
- Developing revenue drivers
- Preparing budgets
- Building rolling forecasts
- Modelling cash flow
- Testing scenarios
- Reviewing working-capital assumptions
- Preparing investor models
- Supporting fundraising analysis
- Connecting forecasts to valuation
- Developing management reporting
- Providing CFO advisory
Businesses that need stronger accounting information before modelling can also use Adamjee’s bookkeeping services.
For strategic financial leadership, CFO advisory services can help management connect financial analysis with business decisions.
Where valuation is involved, the Business Valuation Kenya pillar provides a broader framework for understanding how financial forecasts feed into valuation.
For businesses reviewing their wider financial position, audit and assurance services can provide another layer of financial reporting and assurance support.
Tax considerations can be addressed through tax compliance and advisory services.
These services create a broader finance framework around the model rather than treating the spreadsheet as an isolated document.
Final Takeaway: Your Model Should Challenge the Business Plan
The best financial model is not the spreadsheet with the most formulas. It is the model that makes the business assumptions visible, tests uncertainty and gives management reliable information for making decisions.
The five major financial model mistakes startup founders should watch for are:
1. Forecasting revenue without measurable business drivers.
2. Building only an optimistic scenario.
3. Confusing accounting profit with cash.
4. Hardcoding projected numbers instead of using dynamic assumptions.
5. Making the spreadsheet complicated without designing it around a decision.
There is a common lesson behind all five.
A financial model should not be designed to prove that the founder’s plan will work.
It should be designed to test whether the plan works.
Ask:
What happens if sales are 20% lower?
What happens if customers pay 30 days later?
What happens if gross margins fall?
What happens if hiring costs increase?
What happens if fundraising takes six months longer?
What happens if the expansion requires more working capital than expected?
A good model gives management those answers before the business has to experience them.
That is why correcting financial model mistakes startup founders make is not simply a spreadsheet exercise.
It is a financial risk-management exercise.
For founders preparing to raise capital, expand operations, obtain financing, acquire another business or professionalise their finance function, a properly reviewed financial model can become one of the most useful management tools in the company.
Gain Clarity and Confidence in Your Finances
Navigate the complexities of compliance, tax, and financial management with a trusted partner. Adamjee Auditors, a member of Santa Fe Associates International (SFAI), provides world-class audit, tax, and advisory services to help your business achieve its goals.
Schedule a consultation with our expert team in Nairobi or Mombasa to discuss your business needs.
Nairobi Office
1st Floor, Le’Mac Building, Church Road, off Waiyaki Way, Westlands
+254 717 908 241
madamjee@adamjeeauditors.co.ke
Mombasa Office
Suite 401, Motorwalla Building, Jomo Kenyatta Road
+254 750 053 053
info@adamjeeauditors.co.ke
Adamjee Auditors