- The Finance Act, 2026 (Act No. 19 of 2026) amended the Tax Procedures Act. Most changes took effect on 1 July 2026, and the export-declaration rule for importers took effect on 1 September 2026.
- Amnesty (section 37E): penalties, interest and fines on tax due up to 31 December 2025 can be waived if you apply and pay all outstanding principal tax by 31 December 2026.
- Pre-populated returns (section 75): KRA may issue a return built from its own data by the end of January, and the taxpayer must confirm or amend it within two months.
- A penalty is payable only after KRA issues a written demand, which may be sent electronically, giving at least 30 days to pay (section 89(3)). For failures to invoice, file or pay electronically, the amended section 86 also requires KRA to ask for your reasons first.
- KRA can now assess income from PAYE and withholding tax declarations, eTIMS data and third-party information (section 29A). Such assessments can be objected to under section 51.
- The objection rules did not change. You have 30 days to object, and KRA has 60 days to decide a valid objection or it is deemed allowed.
- The eTIMS deductibility rule (Income Tax Act section 16(1)(c)) predates 2026. KRA says that from the 2026 year of income, all declared income and expenses must be supported by valid eTIMS/TIMS invoices.
The tax procedures act 2026 kenya amendments, made by the Finance Act, 2026, change parts of how businesses deal with the Kenya Revenue Authority (KRA). They affect tax filing, assessments, penalty handling, debt recovery and tax arrears, while the rules on objections stay as they were.
For businesses in Nairobi, Mombasa, and across Kenya, understanding kra law changes 2026 is no longer optional—it directly impacts cash flow, compliance risk, and audit exposure.
This guide, updated in October 2026, explains what the Finance Act, 2026 actually changed in the Tax Procedures Act, and what it left unchanged.
Overview of the Tax Procedures Act Amendments in 2026
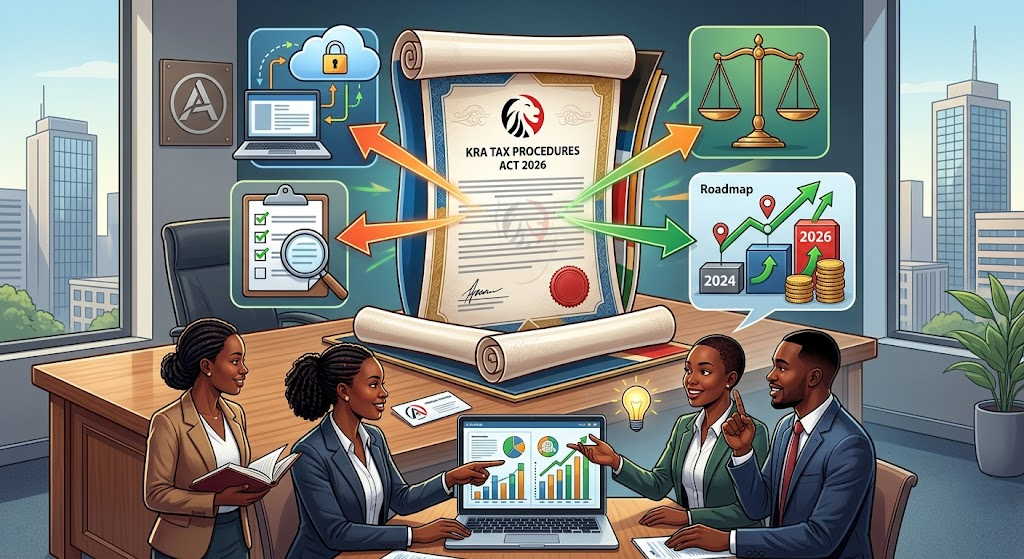
The 2026 amendments to the Tax Procedures Act were made by the Finance Act, 2026 (Act No. 19 of 2026), enacted in June 2026. Most took effect on 1 July 2026; the new export-documentation rule for importers took effect on 1 September 2026. As at October 2026, the main changes are:
- Tax amnesty (section 37E): penalties, interest and fines on tax due up to 31 December 2025 can be waived if the taxpayer applies and pays all outstanding principal tax by 31 December 2026.
- Pre-populated returns (section 75): KRA may generate a return from the information it holds, issued by the end of January, which the taxpayer must confirm or amend within two months.
- Electronic system failures (section 86): before penalising a failure to issue an electronic tax invoice, file electronically or pay electronically, KRA must issue a written notice asking for reasons.
- Waivers (section 89): the Commissioner may waive penalties and interest of up to KES 2 million caused by an error in an electronic tax system.
- Assessments from KRA data (section 29A): KRA may assess income using PAYE and withholding tax declarations, eTIMS data, third-party information and other records.
- Tax avoidance (section 18A): the anti-avoidance rule now sits in the Tax Procedures Act, letting KRA assess tax as if an avoidance scheme had not been carried out.
- Levies collected by KRA (section 39B): unpaid fees, levies and charges that KRA collects can be recovered as if they were unpaid tax.
- Other changes: reinstatement of the same PIN for deregistered persons, information returns for virtual asset service providers, and a duty on importers to keep export declarations for five years.
The Act did not change the objection deadlines or the general late-filing penalties, and a penalty still becomes payable only after a written demand from KRA.
The changes build on systems KRA already uses, including:
- eTIMS invoice validation systems
- Third-party returns and withholding tax data that KRA can use to raise assessments (section 29A)
- Validation of declared income and expenses against eTIMS, withholding tax and customs import records, which KRA applies from the 2025 year of income
In practice, KRA increasingly compares what taxpayers declare with the data it already holds.
Digital Enforcement and KRA Data
Electronic invoicing, filing and payment were already required before 2026. What the Finance Act, 2026 changed is how KRA uses the data and how it handles failures: a new section 29A expressly lets it issue income assessments based on data it already holds, but it must ask for an explanation before penalising a failure to use the electronic tax system.
What this means in practice:
- eTIMS-supported expenses: an existing Income Tax Act rule (section 16(1)(c)), not a 2026 amendment; KRA says that from the 2026 year of income all declared income and expenses must be supported by valid eTIMS/TIMS invoices
- Assessments based on PAYE and withholding tax declarations, eTIMS data and third-party information (section 29A)
- A written notice asking for reasons before any penalty for failing to invoice, file or pay electronically (section 86)
Businesses should make sure their purchases are supported by eTIMS invoices unless the transaction is excluded, for example emoluments, imports, interest and withholding tax payments (section 23A(4) of the Tax Procedures Act).
For structured compliance support, firms can rely on Tax Compliance Advisory and Audit & Assurance Services.
Changes in Tax Filing Requirements Under Tax Procedures Act 2026 Kenya
The main filing change is the pre-populated return: KRA may issue a return built from the information it already holds, and the taxpayer must confirm or amend it within two months of issue. Separately, KRA says that from 1 January 2027 individuals must file income tax returns by the last day of the fourth month after the year of income (30 April for most people), instead of 30 June. Late filing penalties still become payable only once KRA issues a written demand giving at least 30 days to pay.
Key updates:
- Zero-return filings remain mandatory
- Pre-populated returns issued by the end of January, to be confirmed or amended within two months (section 75)
- Income assessments that KRA may raise from eTIMS, PAYE, withholding tax and third-party data (section 29A)
Businesses must adopt structured filing calendars and integrated accounting systems.
Tax Disputes and Objections: What Stayed the Same
The Finance Act, 2026 did not change the objection rules in section 51 of the Tax Procedures Act. As at October 2026, a taxpayer has 30 days from being notified of a tax decision to lodge a notice of objection, and KRA must decide a valid objection within 60 days or it is deemed allowed. Assessments raised under the new section 29A can be objected to in the same way.
Key points:
- Objections must be lodged within 30 days and state precise grounds, with all relevant documents attached
- Objections must be lodged in writing, and KRA may require documents such as objections to be lodged through its electronic system (section 75(1))
- For an objection to an assessment to be valid, the undisputed tax must be paid or an extension of time to pay applied for
This makes documentation readiness essential for all taxpayers.
Penalties Under the Tax Procedures Act After 2026
The 2026 amendments did not remove the written-demand step. Under section 89(3), a penalty is payable only after KRA notifies the taxpayer in writing of the amount and a due date at least 30 days later; that notice may be issued electronically. For failures to issue an electronic tax invoice, file electronically or pay electronically, the amended section 86 adds a further step: KRA must first ask for reasons. If it is not satisfied, the penalty is the higher of 5% of the tax due and KES 100,000 for a company, or KES 10,000 for an individual.
Key implications:
- Late filing penalties under section 83 are unchanged: for example, the higher of 5% of the tax due or KES 10,000 for a VAT return, and for most income tax returns the higher of 5% or KES 20,000 (non-individuals) or KES 2,000 (individuals)
- Late payment interest on unpaid tax runs from the original due date; penalties and interest of up to KES 2 million caused by an electronic tax system error can be waived by the Commissioner (section 89(5B))
- Disallowance of unsupported expenses
This increases financial pressure on SMEs with weak bookkeeping systems.
eTIMS and Deductible Expenses
eTIMS was already central to compliance before 2026. Under section 16(1)(c) of the Income Tax Act, business expenditure must be supported by a valid electronic tax invoice to be deductible, and KRA has said that from the 2026 year of income all declared income and expenses must be supported by valid eTIMS/TIMS invoices. The Finance Act, 2026 adds eTIMS data to the information KRA may use to raise an assessment (section 29A).
Key requirements:
- Sales must be invoiced through eTIMS or TIMS unless KRA has exempted the transaction
- Supplier invoices must be verifiable
- Expense deductions require digital validation
Businesses without proper eTIMS integration face high audit exposure.
Strengthening systems through Bookkeeping Services is now essential.
Paying Tax Arrears and the 2026 Amnesty
The Finance Act, 2026 did not create a new payment-plan regime. Under section 33, a taxpayer can still apply in writing for more time to pay or to pay in instalments, and late payment interest runs from the original due date. Under the 2026 amnesty, a person with principal tax outstanding for periods up to 31 December 2025 applies for the amnesty and proposes a payment plan, but all the principal must be paid by 31 December 2026.
Key updates:
- Amnesty payment plans must clear all principal tax by 31 December 2026
- Unpaid fees, levies and charges collected by KRA recoverable as if they were tax, with amounts up to KES 100,000 recoverable summarily (section 39B)
- Any amnesty balance still unpaid on 31 December 2026 attracts interest and penalties with no further amnesty
Businesses facing cash flow constraints must engage structured financial planning via CFO Advisory Services.
Impact on SMEs and Corporate Taxpayers in KRA Law Changes 2026
For SMEs, the practical effect of the 2026 changes is that gaps between their own records and the data KRA holds are more likely to come to light, through pre-populated returns and data-based assessments. Any business with arrears for periods up to 31 December 2025 should also note the amnesty deadline of 31 December 2026.
Key impacts:
- Assessments where filed returns differ from eTIMS, PAYE or withholding tax data (section 29A)
- Increased documentation requirements
- Pre-populated returns to check against the business’s own records (section 75)
Businesses must upgrade internal systems to remain compliant.
Record Keeping Requirements Under Tax Procedures Act 2026 Kenya
The general record-keeping rule did not change in 2026: records must be kept for five years from the end of the reporting period they relate to. The new obligation is for importers, who from 1 September 2026 must obtain and keep the export declaration from the country of export for five years (section 23B).
Required records include:
- Digital invoices
- Payroll documentation
- Bank statements
- Supplier contracts
Proper bookkeeping systems are critical to avoid estimated assessments.
The 2026 changes continue KRA’s move towards data-driven tax administration. With pre-populated returns and assessments based on third-party data, KRA will often know what a return should show before it is filed.
Key regulatory direction:
- Greater use of third-party, withholding tax and eTIMS data in assessments (section 29A)
- Pre-populated returns built from KRA data (section 75)
- Validation of declared income and expenses against eTIMS, withholding tax and customs import records
- Increased reliance on digital verification systems
As part of the SFAI Global network, Adamjee Auditors applies global audit standards tailored to Kenya’s evolving regulatory framework.
Businesses can strengthen compliance readiness through:
Conclusion
The tax procedures act 2026 kenya amendments change specific parts of Kenya’s tax administration rather than the whole system. With pre-populated returns, assessments based on KRA’s own data and an amnesty that closes on 31 December 2026, businesses should check their records and outstanding balances now.
The key takeaway is that the 2026 changes add an amnesty deadline, pre-populated returns and data-based assessments, while the objection and late-filing rules stay as they were.