A working capital forecast SME approach becomes essential when customers take 90 days to pay. A business can report strong sales and accounting profit while still running short of cash because invoices remain unpaid for months.
For a Kenyan SME selling on credit, this timing difference can determine whether the business can comfortably fund payroll, inventory, suppliers, taxes and loan repayments or whether it needs an overdraft, additional equity or tighter credit controls.
A working capital forecast SME model translates the operating cycle into expected cash requirements. It asks a practical question:
How much money does the business need to keep operating while it waits for customers to pay?
If a company invoices KSh 10 million in January and customers pay after 90 days, the business should not assume that the entire KSh 10 million will be available in January.
The revenue may be recognized before the cash arrives.
That gap is working capital.
A reliable working capital forecast SME therefore connects sales, receivables, inventory, supplier credit, operating expenses and cash flow rather than looking at profit alone.
What Is a Working Capital Forecast for an SME?
A working capital forecast SME model estimates how much cash will be tied up in receivables, inventory and other operating assets after considering supplier credit and other current liabilities. It helps management identify funding needs before a cash shortage occurs.
Working capital generally concerns the short-term resources and obligations involved in running the business.
Common components include:
- Trade receivables
- Inventory
- Trade payables
- Prepayments
- Accrued expenses
- Other operating current assets
- Other operating current liabilities
- Cash
The operating cycle is especially important.
A business may:
- Purchase inventory.
- Hold the inventory.
- Sell to a customer on credit.
- Record a receivable.
- Wait for payment.
- Receive cash.
- Use the cash to fund the next operating cycle.
The longer that process takes, the more funding the business may need.
A commonly used working-capital-cycle formula is:
Inventory Days + Receivable Days − Payable Days = Cash Conversion Cycle
The cash conversion cycle measures the time between cash being committed to operations and cash being recovered from customers, after considering supplier credit.
Why 90-Day Customers Create a Cash-Flow Problem
A 90-day customer payment period can create a substantial funding gap even when sales and profit are growing. A working capital forecast SME model makes that gap visible month by month.
Consider a Kenyan engineering supplier that invoices:
KSh 12 million per month
Customers pay after approximately 90 days.
The business may record:
January revenue: KSh 12 million
But if January invoices are collected in April, January’s sales do not immediately provide January cash.
If February and March sales continue at KSh 12 million each, the business could have approximately:
- January receivables: KSh 12M
- February receivables: KSh 12M
- March receivables: KSh 12M
before January’s invoices are substantially collected.
That represents approximately:
KSh 36 million of outstanding customer invoices
before considering collections, credit notes and other timing factors.
The business may therefore need to finance tens of millions of shillings even though the income statement shows strong revenue.
This is why a working capital forecast SME should be built before management commits to aggressive growth.
Profit Is Not the Same as Cash
Profit measures accounting performance; cash measures liquidity. A working capital forecast SME helps management understand why profitable sales can still create a cash shortage.
Suppose an SME records:
Revenue: KSh 100 million
Expenses: KSh 80 million
Accounting profit: KSh 20 million
That does not necessarily mean KSh 20 million has entered the bank.
If a large portion of the revenue was sold on 90-day credit, cash may still be tied up in receivables.
The same applies to inventory.
A company may purchase KSh 15 million of stock today but sell the stock several months later.
The accounting and cash-flow effects occur at different times.
This is why businesses preparing forecasts should connect their profit forecast to the balance sheet and cash-flow forecast.
Adamjee’s CFO advisory services include cash-flow management and financial modelling, which can help businesses turn accounting information into forward-looking financial analysis.
Start With Your Actual Customer Payment Behaviour
Do not build a 90-day working capital forecast SME simply because customer contracts say payment is due in 90 days. Analyse actual collection behaviour because contractual terms and real cash receipts can differ.
A business may have:
Contractual payment terms: 30 days
but actual average collections may be:
45 days
Or it may have:
Contractual payment terms: 90 days
while some customers consistently pay after:
110 or 120 days
The forecast should reflect evidence.
Review:
- Invoice dates
- Due dates
- Actual payment dates
- Customer balances
- Credit notes
- Disputed invoices
- Part payments
- Bad debts
- Customer concentration
- Historical collection patterns
Calculate:
Receivable Days = Average Trade Receivables ÷ Credit Sales × 365
Financial modelling guidance commonly uses receivable days, inventory days and payable days to forecast working-capital balances.
For a monthly model, however, it is often better to use an actual collection schedule rather than relying solely on an annual average.
Build a 90-Day Receivables Schedule
The most useful working capital forecast SME model does not merely show one annual receivables figure. It maps expected customer collections by month so management can see exactly when cash should arrive.
Suppose the business invoices:
| Month | Credit Sales |
|---|---|
| January | KSh 10M |
| February | KSh 12M |
| March | KSh 15M |
| April | KSh 13M |
If customers generally pay after 90 days, the forecast could initially assume:
| Invoice Month | Expected Collection |
|---|---|
| January | April |
| February | May |
| March | June |
| April | July |
This creates a collection calendar.
The model can then become more realistic.
Suppose management knows that:
- 60% is collected within 90 days
- 25% arrives in 91–120 days
- 10% arrives in 121–150 days
- 5% becomes disputed or delayed
The forecast can allocate collections accordingly.
That is more informative than simply saying:
Receivables = 90 days of sales.
Calculate the Receivables Funding Requirement
A 90-day payment cycle can tie up a large amount of cash. A working capital forecast SME should quantify the receivables funding requirement instead of treating customer credit as a normal sales assumption.
A simplified annual example:
Annual credit sales: KSh 120 million
Receivable period: 90 days
Using:
KSh 120M ÷ 365 × 90
the estimated receivables balance is approximately:
KSh 29.6 million
That means almost KSh 30 million may be tied up in customer balances under a simplified constant-sales assumption.
If the company reduces collection time to 60 days:
KSh 120M ÷ 365 × 60 = approximately KSh 19.7 million
The reduction is approximately:
KSh 9.9 million
The business has effectively released almost KSh 10 million of working capital without increasing sales.
This is one of the most important insights a working capital forecast SME can provide.
Forecast Inventory Separately
Receivables are only one part of working capital. A working capital forecast SME should also model inventory because stock purchased before it is sold can consume cash long before revenue is collected.
Suppose annual cost of sales is:
KSh 60 million
and the business holds:
60 inventory days
A simplified inventory forecast is:
KSh 60M ÷ 365 × 60 = approximately KSh 9.86 million
If inventory days rise to 90:
KSh 60M ÷ 365 × 90 = approximately KSh 14.79 million
The additional stock requirement is approximately:
KSh 4.93 million
This is cash that could otherwise be available for payroll, debt repayment, expansion or other operating needs.
For distributors and manufacturers, inventory assumptions can therefore be just as important as customer collection assumptions.
Include Supplier Payment Terms
Supplier credit can partially finance the operating cycle. A working capital forecast SME should therefore forecast accounts payable alongside receivables and inventory.
Suppose annual purchases or cost of sales are:
KSh 60 million
and suppliers provide:
45 days credit
A simplified payable balance is:
KSh 60M ÷ 365 × 45 = approximately KSh 7.40 million
That KSh 7.40 million represents supplier financing within the operating cycle.
Now compare the simplified position:
- Receivables: KSh 29.6M
- Inventory: KSh 9.9M
- Payables: KSh 7.4M
Net operating working capital is approximately:
KSh 29.6M + KSh 9.9M − KSh 7.4M = KSh 32.1M
The exact accounting presentation will depend on the business and its current assets and liabilities, but the calculation demonstrates why growth can require substantial funding.
The working-capital cycle formula similarly subtracts payable days from inventory and receivable days.
Calculate the Cash Conversion Cycle
The cash conversion cycle shows how long cash is tied up in the operating process. For a working capital forecast SME, it provides a useful high-level measure of whether growth is consuming or releasing liquidity.
Suppose an SME has:
Inventory Days: 60
Receivable Days: 90
Payable Days: 45
Then:
Cash Conversion Cycle = 60 + 90 − 45
Cash Conversion Cycle = 105 days
The business is therefore financing approximately 105 days of its operating cycle under these assumptions.
This does not mean exactly 105 days of every expense must be funded.
It means the operating cycle is consuming cash for a substantial period before it is recovered.
Management should then ask:
Can the business finance that cycle internally?
If not:
How much external funding is required?
Build the Forecast Monthly, Not Just Annually
A 90-day collection period makes monthly forecasting particularly important. An annual working capital forecast SME can hide temporary cash shortages that become obvious when receivables and payments are mapped month by month.
Consider a business with seasonal sales.
It may have:
- Low sales in January
- Moderate sales in February
- Strong sales in March
- Peak sales in April
- Collections beginning three months after invoicing
An annual average could suggest that the company has sufficient liquidity.
A monthly forecast may reveal that the company runs out of cash in February before the stronger collections arrive later in the year.
This is why a rolling 12-month cash-flow forecast is often more useful for liquidity management.
A monthly cash-flow forecast can incorporate operating assets and liabilities, including receivables, inventory and payables, and use working-capital ratios to project future balances.
Build a Rolling Working Capital Forecast
A rolling working capital forecast SME should be updated regularly as actual sales, collections, inventory movements and supplier payments become available. The forecast should replace assumptions with actual information as each month closes.
For example, in January management may forecast:
February–January next year
After January closes, February becomes the next forecast month and actual January results replace assumptions.
The process becomes:
Actual January → Forecast February–January
Then:
Actual February → Forecast March–February
This gives management a continuously updated view of the next 12 months.
A rolling forecast is especially useful when:
- Sales are volatile
- Customers pay slowly
- Inventory requirements change quickly
- Supplier terms are unstable
- The company is growing rapidly
- Cash reserves are limited
- Financing is expensive
Use a Receivables Ageing Schedule
A receivables ageing report provides the evidence behind the assumptions in a working capital forecast SME. Forecasting should distinguish current invoices from overdue and potentially doubtful balances.
A useful ageing report may include:
| Age | Amount |
|---|---|
| Current | KSh 8M |
| 1–30 days overdue | KSh 4M |
| 31–60 days | KSh 3M |
| 61–90 days | KSh 5M |
| 91–120 days | KSh 2M |
| Over 120 days | KSh 3M |
Now suppose management assumes customers pay in 90 days.
The ageing report may reveal that a significant portion is already older than 90 days.
That should change the forecast.
The business may need to distinguish:
- Expected collections
- Late collections
- Disputed balances
- Doubtful balances
- Bad debts
A forecast based on the contractual due date alone can therefore overstate expected cash.
Do Not Assume Every Customer Pays at the Same Speed
Customer-level payment behaviour can materially improve a working capital forecast SME. A 90-day average may hide customers who pay in 30 days and others who consistently take 150 days.
Consider three major customers:
| Customer | Monthly Sales | Typical Collection |
|---|---|---|
| Customer A | KSh 4M | 45 days |
| Customer B | KSh 3M | 90 days |
| Customer C | KSh 3M | 150 days |
The overall average may be around 90 days.
But the cash-flow risk is concentrated in Customer C.
If Customer C represents a large share of sales, a single average collection period may conceal the risk.
The forecast should therefore consider:
- Customer concentration
- Individual payment patterns
- Contract terms
- Credit limits
- Disputes
- Historical ageing
- Expected order growth
This becomes especially important when one large customer accounts for a significant proportion of revenue.
Model the Cost of Growth
Growth can increase the working-capital requirement before it increases available cash. A working capital forecast SME should therefore calculate how much additional funding each incremental unit of sales requires.
Imagine a distributor growing from:
KSh 100 million sales → KSh 150 million sales
If receivables remain at 90 days, the additional KSh 50 million of annual sales could require approximately:
KSh 50M ÷ 365 × 90 = KSh 12.33M
of additional receivables under a simplified assumption.
If inventory also rises by KSh 5 million and supplier financing increases by KSh 3 million, the incremental net working-capital requirement could be approximately:
KSh 12.33M + KSh 5M − KSh 3M = KSh 14.33M
The exact requirement depends on the business model and timing.
But the principle is important:
More sales can require more financing.
Management should therefore forecast the cash cost of growth before approving expansion.
What If Customers Pay in 120 Days Instead?
A working capital forecast SME should test longer collection periods because a 90-day assumption may become unrealistic during periods of customer stress or weak collections.
Suppose annual credit sales are:
KSh 120 million
At 90 days:
KSh 120M ÷ 365 × 90 = KSh 29.6M
At 120 days:
KSh 120M ÷ 365 × 120 = KSh 39.5M
The additional receivables requirement is approximately:
KSh 9.9 million
That is a major financing requirement created solely by a 30-day deterioration in collections.
This is why management should not only ask:
“What happens if sales fall?”
It should also ask:
“What happens if customers take longer to pay?”
What If Customers Pay in 60 Days Instead?
Improving collections can release working capital without requiring additional sales. A working capital forecast SME should therefore model both downside and improvement scenarios for customer payment periods.
Using the same KSh 120 million annual sales:
At 90 days:
KSh 29.6M receivables
At 60 days:
KSh 19.7M receivables
Potential cash released:
Approximately KSh 9.9M
That could potentially reduce the need for:
- Bank overdraft
- Short-term borrowing
- Shareholder loans
- Emergency equity injections
It may also reduce financing costs.
The forecast therefore becomes a management tool for identifying operational improvements.
Connect Working Capital to a Three-Statement Model
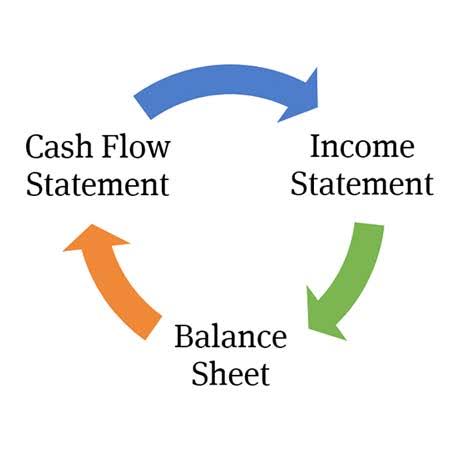
A working capital forecast SME should ultimately feed the balance sheet and cash-flow statement. Receivables, inventory and payables are not just reporting numbers; changes in them directly affect operating cash flow.
The basic relationships are:
Sales → Receivables
Cost of sales/purchases → Inventory
Purchases → Payables
Then:
Change in receivables → Operating cash-flow adjustment
Change in inventory → Operating cash-flow adjustment
Change in payables → Operating cash-flow adjustment
A business that increases receivables has generally used cash.
A business that increases payables has generally preserved cash.
A business that reduces inventory can release cash.
This is why working capital should not be modelled independently from the three financial statements.
For businesses needing a broader integrated model, Adamjee’s CFO advisory and financial modelling services can support cash-flow planning, financial modelling and management reporting.
Include Other Current Assets and Liabilities
Receivables, inventory and payables are the major working-capital accounts, but a complete working capital forecast SME should consider other material current assets and liabilities.
Depending on the business, these may include:
Prepayments
Examples include:
- Insurance
- Rent paid in advance
- Software subscriptions
- Annual service contracts
Accrued expenses
Examples include:
- Utilities
- Professional fees
- Payroll-related costs
- Services received but not yet invoiced
Tax liabilities
Potentially including:
- VAT
- Withholding taxes
- Payroll-related taxes
- Income-tax obligations
Other receivables
These might include:
- Staff advances
- Supplier deposits
- Other recoverable amounts
These balances can affect both the balance sheet and cash-flow forecast.
Include Tax Timing in the Cash Forecast
Tax obligations can create cash outflows that do not perfectly match the month in which revenue or expenses are recognized. A working capital forecast SME should therefore model material tax payment timing rather than relying only on accounting profit.
For Kenyan businesses, this also requires accurate underlying records.
KRA states that, effective 1 January 2026, income and expenses declared in income-tax returns are being validated against data including TIMS/eTIMS, withholding-tax gross amounts and customs import records.
KRA also states that persons engaged in business are generally required to onboard eTIMS and issue electronic tax invoices, with specified exceptions.
For the forecast, the important point is that tax-related cash requirements should be visible in the liquidity plan.
The forecast should not assume:
Profit = available cash
Instead, it should show when relevant tax liabilities become payable.
Where accounting records need improvement, bookkeeping and accounting services can help establish a cleaner foundation for forecasting.
Use Working Capital Ratios
Ratios make a working capital forecast SME easier to monitor because management can track collection, inventory and supplier behaviour over time rather than looking only at shilling balances.
Important measures include:
Receivable Days
Average Receivables ÷ Credit Sales × 365
Inventory Days
Average Inventory ÷ Cost of Sales × 365
Payable Days
Average Payables ÷ Cost of Sales or Purchases × 365
Cash Conversion Cycle
Receivable Days + Inventory Days − Payable Days
Working Capital as a Percentage of Revenue
Net Operating Working Capital ÷ Revenue × 100
The appropriate denominator depends on the business and accounting structure.
The purpose is not to chase a particular ratio blindly.
It is to identify changes.
If receivable days move:
75 → 90 → 110
management should investigate.
If inventory days move:
45 → 60 → 85
there may be excess stock, slower sales or purchasing issues.
If payable days fall:
60 → 45 → 30
supplier financing may be declining.
These movements can provide early warning of a cash-flow problem.
Build a Working Capital Stress Test
A strong working capital forecast SME should show what happens when multiple assumptions deteriorate simultaneously. Stress testing can reveal funding gaps before they become urgent.
Consider a downside scenario where:
- Sales fall 10%
- Collection period increases from 90 to 120 days
- Inventory days increase from 60 to 75
- Supplier terms fall from 45 to 30 days
Each change affects liquidity.
The combined effect can be substantially larger than any individual change.
Management should then ask:
- How much additional funding is required?
- When does the funding gap occur?
- Can the bank facility cover it?
- Can suppliers extend terms?
- Can customers be encouraged to pay earlier?
- Can inventory purchases be reduced?
- Can discretionary spending be delayed?
- Is additional equity required?
The forecast converts these questions into measurable scenarios.
Working Capital Forecast SME Checklist
Before relying on a working capital forecast SME, make sure the model uses realistic collection behaviour, inventory assumptions and supplier terms. The forecast should also show the monthly cash consequences of those assumptions.
Check that the forecast includes:
- Monthly sales forecast
- Credit sales
- Customer payment terms
- Actual collection history
- Receivables ageing
- Customer concentration
- Receivable days
- Inventory forecast
- Inventory days
- Purchases forecast
- Supplier payment terms
- Payable days
- Prepayments
- Accrued expenses
- Relevant tax liabilities
- Opening cash
- Monthly cash collections
- Monthly supplier payments
- Payroll payments
- Capital expenditure
- Debt repayments
- Financing inflows
- Closing cash
- Base scenario
- Downside scenario
- Collection improvement scenario
- Working-capital ratios
- Cash conversion cycle
- Funding requirement
If the business has 90-day customers, the most important question is not whether sales are growing.
It is whether the business has enough liquidity to finance the period between making the sale and receiving the cash.
How Adamjee Auditors Can Help With Working Capital Forecasting
A working capital forecast SME is most useful when it is connected to accurate accounting records, cash-flow forecasts and management decisions. Adamjee Auditors can help SMEs translate financial information into practical forecasts and cash-management plans.
Support may include:
- Working-capital forecasting
- Cash-flow forecasting
- Financial modelling
- Budgeting
- Budget-versus-actual analysis
- Management accounts
- Receivables analysis
- Cash conversion analysis
- Financing requirement analysis
- Investor forecasting
- CFO advisory
- Tax and accounting support
Adamjee’s CFO advisory services cover financial modelling and cash-flow management, which can support businesses dealing with extended customer payment cycles.
For businesses preparing for financing, acquisition or investment, working-capital analysis can also form part of broader financial due diligence.
Final Takeaway
A working capital forecast SME should show when money is expected to leave the business, when customers are expected to pay and how much funding is required to bridge the gap. For businesses with 90-day customers, this can be more important to survival than the headline profit figure.
The basic logic is simple:
Sales create receivables.
Purchases create inventory.
Supplier credit creates payables.
Receivables, inventory and payables determine the operating cash cycle.
If customers take 90 days to pay, the business needs a financial plan that reflects those 90 days.
Using a simplified example, KSh 120 million of annual credit sales at 90-day collection terms can produce approximately KSh 29.6 million of receivables.
If collections deteriorate to 120 days, the requirement can rise to approximately KSh 39.5 million.
If collections improve to 60 days, the receivables requirement can fall to approximately KSh 19.7 million.
Those differences can determine whether an SME needs additional financing or can fund growth internally.
The strongest working capital forecast SME therefore does not merely predict the balance sheet.
It helps management answer practical questions:
How much cash is tied up?
When will it be released?
What happens if customers pay later?
What happens if inventory increases?
How much supplier credit is available?
When will the business need additional funding?
What operational actions can release cash?
That is the real purpose of working-capital forecasting.
Gain Clarity and Confidence in Your Finances
Navigate the complexities of compliance, tax, and financial management with a trusted partner. Adamjee Auditors, a member of Santa Fe Associates International (SFAI), provides world-class audit, tax, and advisory services to help your business achieve its goals.
Schedule a consultation with our expert team in Nairobi or Mombasa to discuss your business needs.
Nairobi Office
1st Floor, Le’Mac Building, Church Road, off Waiyaki Way, Westlands
+254 717 908 241
madamjee@adamjeeauditors.co.ke
Mombasa Office
Suite 401, Motorwalla Building, Jomo Kenyatta Road
+254 750 053 053
info@adamjeeauditors.co.ke
Adamjee Auditors